What Crypto Is
Crypto is short for cryptocurrency. It refers to decentralized digital currencies and assets secured by cryptography and blockchain technology. Cryptocurrencies are not issued by governments or central banks. They are created, exchanged, and overseen by groups of participants operating through distributed computer networks.
A crypto coin is generally designed to act as currency by transferring value or paying for transactions. A crypto token can represent utility, governance rights, ownership, or a claim connected to another asset. Non-fungible tokens, or NFTs, are unique digital records that can represent ownership or authenticity of a digital, physical, or abstract item. From an investing perspective, coins and tokens can be traded and can appreciate in value, although their designs, risks, and functions differ.
Cryptography helps make counterfeiting and double-spending extremely difficult. Blockchain technology records and verifies transactions across many computers. A cryptocurrency is distinct from government-issued money because it is created and maintained through a network and protocol rather than issued by a central monetary authority.
Crypto can be used for peer-to-peer transfers, cross-border payments, savings, trading, decentralized finance, tokenized assets, digital identity, supply-chain systems, gaming, social media, and other applications. The underlying asset may be designed primarily as money, as a computational resource, as governance power, as a claim on another asset, or as a collectible. Those differences are important when evaluating whether a project produces cash flow, supports a working application, creates utility, or depends mainly on demand for its token.
Blockchain Basics
A blockchain is a decentralized ledger of transactions. It is software running on a network of independent computers or computer clusters. In proof-of-work systems, miners process and verify transactions, group them into blocks, and receive cryptocurrency rewards. Other systems use validators or other consensus mechanisms.
Blockchain technology can provide several potential properties:
Properties of blockchain
- Transactions can be made directly between participants without a bank or other central intermediary.
- In many public blockchains, transactions are visible to anyone.
- Recorded transactions are difficult or impossible to reverse.
- Network records can be distributed across many computers.
- Rules and transaction histories can be transparent and publicly inspectable.
- Smart-contract platforms can execute code and automate applications.
Immutability also creates a limitation. A transaction that cannot be reversed cannot easily be corrected if it was entered incorrectly. A faulty application, compromised private key, flawed smart contract, or erroneous transfer can therefore have lasting consequences.
Bitcoin transactions are processed through proof-of-work mining. Ethereum also supports smart contracts and decentralized applications. Other networks use proof of stake, federated consensus, delegated consensus, or project-specific mechanisms.
Common Terms You Should Know
Before you invest crypto coin, you need to understand the basic vocabulary:
Key crypto terms
- Altcoins - Cryptocurrencies other than Bitcoin, including networks such as Ethereum, Litecoin, Solana, XRP, and many others.
- Token - A digital unit issued on a blockchain. A token can provide utility, governance rights, economic participation, or ownership of another asset.
- Wallet - An application or device used to store, send, or receive cryptocurrency.
- Market capitalization - The total market value of a cryptocurrency's circulating supply.
- Bull market - A period when prices are generally rising.
- Bear market - A period when prices are generally falling.
- Whitepaper - A technical and economic document describing a project's technology, goals, roadmap, or token design.
- Gas fee - A transaction cost charged by a blockchain to process an operation, especially on networks that support smart contracts.
- Liquidity - The ease with which an asset can be bought or sold without causing a large price movement.
- Custody - The control and safeguarding of a private key or account holding crypto.
- Smart contract - Software running on a blockchain that executes predefined rules.
- Decentralized finance, or DeFi - Financial applications built on blockchain networks.
- Proof of Work, or PoW - A consensus method in which miners perform computational work to validate transactions and produce blocks.
- Proof of Stake, or PoS - A consensus method in which token holders validate transactions and can receive rewards.
- Stablecoin - A crypto asset designed to maintain a value near an external reference, usually a fiat currency, commodity, or basket of assets.
- Presale - A sale of a token before or during its initial public release.
- Airdrop - A distribution of tokens to wallets, often used to encourage network participation.
Bitcoin, Ethereum, and Dogecoin
Bitcoin is generally described as the first and largest cryptocurrency by market capitalization. It was described in 2008 under the pseudonym Satoshi Nakamoto and launched in early 2009. Nakamoto's real identity remains unknown and may belong to one person or a group.
Bitcoin was designed to store and transfer value without a central issuer. Its proof-of-work network makes transaction history difficult to alter and prevents coins from being easily double-spent. New coins are issued to miners as rewards. Its issuance schedule slows over time and is designed to cap supply at 21 million bitcoin.
Ethereum is a blockchain platform with a native currency called Ether, or ETH. Unlike a currency designed only for transfers, Ethereum supports programmable smart contracts. Developers can deploy tokens, decentralized finance applications, games, social applications, and other software on top of the network. Examples of decentralized applications mentioned in beginner material include Uniswap, a crypto trading protocol, and Aave, a crypto lending platform.
An NFT is data with a unique identifier stored on a blockchain. It can act as a public certificate of authenticity or proof of ownership. Common applications include digital art and collectibles, although an NFT can represent physical or abstract property as well.
Dogecoin, or DOGE, is described as a decentralized, open-source cryptocurrency created in 2013 as a simple and accessible alternative to Bitcoin. Aalto Investment Club also describes it as having begun as a joke before experiencing large price growth. Dogecoin is commonly categorized as a meme coin. Whether owning meme coins should be described as investing or gambling is debated in the source material.
Why People Invest in Crypto
The investment case for crypto varies by project. Common arguments include:
Reasons investors hold crypto
- Cryptocurrencies can transfer value without requiring a conventional banking intermediary.
- Some coins are designed for payments, remittances, or settlement.
- A fixed or limited supply may create scarcity.
- Some projects are built for specific technologies such as privacy, smart contracts, artificial intelligence, decentralized trading, payments, or tokenization.
- Crypto may have a different risk and return pattern from conventional stocks, bonds, and real estate.
- A small allocation may provide exposure to an emerging technology or asset class.
- Owning a small amount may reduce the behavioral pressure created by fear of missing out.
- Some investors view bitcoin as "digital gold" or a store of value that does not depend on a government issuer.
- Others value crypto because it can operate continuously, be transferred globally, be held without an intermediary, and have a transparent monetary policy.
- Some stablecoins are intended to combine blockchain transfer capabilities with a value close to a fiat currency.
The case against crypto or against including it in a portfolio includes the following points:
Risks to consider
- Many crypto assets produce no earnings, interest, rent, or other cash flow.
- Their future value may depend primarily on scarcity, adoption, regulation, sentiment, and the price at which another participant is willing to buy.
- Historical returns may not continue.
- Market capitalization can fall sharply, and some projects may fail completely.
- Exchanges, private keys, wallets, bridges, and smart contracts can be compromised.
- Governance can be concentrated even when a network is described as decentralized.
- Regulatory treatment can change.
- Short-term trading can be influenced by hype, social media, insider activity, and liquidity.
- A small percentage of a portfolio can still become a major contributor to portfolio volatility if its value rises far above the target allocation.
- A crypto allocation can rebalance downward during a severe crash.
Market Volatility
Crypto prices are driven by supply and demand. Prices tend to rise when demand grows faster than available supply and fall when selling pressure exceeds demand. Crypto markets have historically experienced large movements over short periods. Weekly changes of 5% to 20% were described as normal in one educational article, even though conditions can be more extreme during bubbles, crashes, regulatory shocks, hacks, or changes in market sentiment.
One comparison of market periods showed:
Historical market periods
- In 2021, Bitcoin gained more than 50%, while Ether gained almost 400%.
- At the time of that article's publication in the 2022 period, Bitcoin and Ether were both down more than 30%, with much of the broader crypto market following the same direction.
- Crypto has experienced multiple bull and bear markets.
- The article described approximate four-year price cycles and noted possible correlation with the stock market and Bitcoin halving events.
- The broader long-term direction was upward despite severe intermediate declines, but the source cautioned that ten years represented a short history and did not prove that prices or cycles would continue in the same way.
Bitcoin rose more than 120% in 2024. In December 2024, it traded above $90,000 and then surpassed $100,000 a few days later. Those figures describe calendar-year or point-in-time performance and do not represent the return of every investor. A personal portfolio can experience a different result because of purchase dates, rebalancing, taxes, fees, and the amount allocated.
Researching a Crypto Project
Research should cover more than a recent price chart or social-media trend. The educational and project-ranking materials identify several areas for review.
Vision and Purpose - Determine what problem the project is trying to solve. A payment project should explain how payments become faster, cheaper, or more accessible. A smart-contract platform should show that applications are being used. An AI project should distinguish between a working product and a future promise. A privacy coin should explain the technology and operational risks involved in privacy.
Team and Development - Review the people building the project, their relevant experience, transparency, and development activity. A team can change, become inactive, or fail to deliver a roadmap. Anonymous teams are not automatically disqualifying, as Bitcoin's creator is unknown, but they can make outside verification harder.
Tokenomics - Evaluate total supply and circulating supply, initial distribution, founder and team allocations, emission and burn mechanisms, vesting schedules, inflation or deflation, token utility, governance rights, staking rewards and their sources, whether fees accrue to token holders, whether token demand comes from network use or only from trading, whether large holders can control supply or market activity, and whether rewards depend on inflation that transfers value from one holder to another.
Working Product - CoinCodex said it favored projects that already had a working product rather than only a roadmap. It focused on coins with a functioning mainnet and tokens used for utility or governance in active protocols.
Liquidity and Availability - Beginner criteria included market capitalization of at least $1 billion, listing on multiple centralized and decentralized exchanges, ability to trade directly against fiat currencies, at least $100 million in 24-hour trading volume, and an established ecosystem with educational and technical resources. These filters can make an asset easier to buy and sell, but they do not remove price risk or guarantee that a project is safe.
Market Capitalization and Price Manipulation - A large market capitalization can indicate broad community interest and make manipulation more expensive because more capital is needed to move the price. It does not prove project quality, prevent a large decline, or eliminate fraud.
Community and Adoption - Community activity, developer activity, users, transactions, fees, and application usage can help distinguish actual adoption from manufactured hype. Reddit, X, Discord, and other social platforms can provide useful information, but coordinated promotion, fake accounts, insider token distribution, and selective screenshots can distort the apparent community.
Whitepapers and Technical Documents - Whitepapers can explain a protocol's architecture, token design, roadmap, consensus rules, and intended use. They should be compared with working code, current development, audits, and actual usage. A whitepaper can describe a goal without proving that the goal has been achieved.
Security - Check whether the project has had exploits, vulnerabilities, bridge attacks, oracle failures, validator concentration, or weak private-key designs. A smart-contract audit can reduce some risks but cannot remove all risks. Security claims from project teams or AI-model vendors should be distinguished from formal audits and independent code review.
Regulation and Tax - Rules can change according to jurisdiction. Questions include whether an asset is treated as a security, commodity, currency, property, or something else; whether gains are taxable; whether staking rewards are taxable; whether exchanges report transactions; and whether withdrawal or transfer restrictions apply.
Setting Your Investment Plan
The sources repeatedly emphasize that the decision should be based on a personal plan rather than the current Bitcoin price.
Risk Tolerance - The amount that can be lost without disrupting savings or other goals should be identified before buying. Smaller, newer tokens can produce larger gains but can also lose most or all of their value. Bitcoin and Ether are often described as more established and liquid, but they remain volatile.
A cited personal allocation used 1% to 5% as an individual range. A financial adviser's 2022 recommendation was no more than 5% of net worth in a play fund. A White Coat Investor author later suggested approximately 5% for a convinced bitcoin believer. These figures show differing personal boundaries rather than a single settled standard.
Time Horizon - Short-term traders seek to buy and sell quickly. Long-term holders plan to keep an asset for months or years. A project may need years to develop, while a trading strategy may be exposed to daily volatility. Time horizon also affects taxes, fees, liquidity needs, and the possibility of a complete loss.
Core Portfolio and Interruptions - Crypto can be treated as one part of a diversified allocation rather than as the entire portfolio. The 98% stock and 2% crypto example was intended to keep crypto from affecting cash flow or disrupting the compounding of the main portfolio.
Dollar-Cost Averaging - Rather than investing one large sum at a specific moment, an investor can purchase smaller amounts over time. Bayes said he might use dollar-cost averaging while prices were falling and generally did not rebalance more than one or two times per year. A commenter recommended investing 2% of new savings each year without rebalancing. These approaches require assumptions about future returns and can perform differently if an asset rises or falls rapidly.
Rebalancing - A written rebalancing rule can specify the target allocation, the lower threshold for buying, the upper threshold for selling, which account supplies cash, which asset receives sale proceeds, how taxes and transaction costs are considered, and what happens if the asset becomes impaired or loses most of its value. Rebalancing captures volatility by selling after appreciation and buying after declines. It can also reduce upside, create taxable gains, add trading costs, and cause repeated purchases during a collapse.
Take Profits - Heather Townsend advised clients who had gains they would hate to lose to consider taking some gains off the table. She noted that several clients who followed similar advice while bitcoin was in the $60,000s felt better about subsequent volatility when bitcoin later moved into the $30,000s.
Buying Your First Crypto
A beginner process described in the sources includes the following steps:
Steps to buy crypto
- Choose a reliable exchange. Kraken was described as the best all-around exchange for beginners in one article, while Coinbase and Binance were also named as large platforms in another educational article. The examples differed by source and did not apply to every jurisdiction.
- Create an account and complete any identity-verification requirements.
- Deposit funds. Large exchanges may support bank transfers and debit or credit card transfers, although available methods depend on location.
- Choose an asset based on the investment plan and research.
- Choose an amount that can be afforded without damaging other financial goals.
- Place a market order for an immediate execution at the available market price or a limit order for a specified maximum or minimum price.
- Record the purchase, cost basis, date, fees, and tax information.
- Decide whether the asset will remain on the exchange or be transferred to self-custody.
- Avoid making decisions solely because of a price increase, headline, social-media trend, or fear of missing out.
CoinCodex recommended starting with smaller amounts and established assets such as Bitcoin and Ethereum. It said beginner investors could later consider lower-market-cap altcoins after learning how the market works.
Storage and Security
The sources present several custody models.
Exchange Custody - An exchange holds the private keys associated with deposited assets. This makes recurring purchases, trading, and transfers convenient. It also introduces counterparty risk. Francis Bayes kept his crypto on a well-established exchange because automatic recurring purchases were the most important feature for him. He said he might transfer some to a wallet later and considered his brokerage-account security acceptable.
Self-Custody - Self-custody gives the owner direct control over private keys. A hardware wallet is commonly recommended for longer-term storage. A backup seed phrase must be protected because anyone who obtains it may be able to take control of the assets. Hardware wallets do not eliminate user error, malware, compromised devices, phishing, or lost backups.
Software and Online Wallets - Software wallets can make sending and receiving convenient. They may be connected to the internet and can be exposed to phishing or compromised applications. The source material emphasizes checking the destination address, protecting accounts, and understanding the custody model.
Choosing a Storage Approach - Francis Bayes prioritized recurring-purchase convenience. CoinCodex and Aalto Investment Club emphasized hardware wallets or self-custody. The comments described a trade-off between convenience and direct control. No source described one method as completely safe.
Stablecoins
Stablecoins are cryptocurrencies designed to maintain a value close to an external reference. Most target the U.S. dollar. Others are linked to commodities, cryptocurrency collateral, or real-world assets such as short-term U.S. Treasuries.
Stablecoins are designed to reduce the volatility associated with ordinary crypto and can be used for payments, cross-border transfers, trading, savings or reserve balances, lending and borrowing, DeFi collateral, exchange settlement, and portfolio rebalancing.
The December 2025 WazirX material described stablecoins as offering fast blockchain transactions, low fees, global access, and less volatility than bitcoin or ether. It also said stablecoins can be independent of banks, although that independence depends on the issuer, reserve custodian, redemption process, smart contract, and blockchain.
Stablecoins are not automatically risk-free. Their value can depend on reserves, counterparties, redemption liquidity, collateral quality, governance, regulation, and market confidence. A token intended to track a fiat currency can trade above or below its target.
USDC - USDC is issued by Circle and is intended to track the U.S. dollar. The December 2025 stablecoin list described it as backed 1:1 by cash and short-term U.S. Treasuries. It is supported by major financial institutions, used on centralized exchanges and in DeFi, and used in cross-border settlement. The list highlighted greater reserve transparency, daily reserve reports, increasing adoption in global payments, and regulatory compliance following tighter U.S. stablecoin rules.
USDT - Tether's USDT was described as the largest stablecoin by market capitalization in 2025 and the most widely traded. It is supported by many exchanges, trading pairs, and DeFi platforms. The stated reserve mix included U.S. Treasuries, cash, money market funds, and other real-world assets. Tether was said to have reduced exposure to risky commercial paper since 2023. Its transparency reports had improved, although audit debates continued.
DAI - DAI is a decentralized stablecoin created by MakerDAO. It was originally backed by cryptocurrency collateral. The December 2025 article said its backing and ecosystem had expanded to include U.S. Treasuries, real-world asset vaults, ETH, and other crypto assets. The list highlighted overcollateralization, governance through the Maker Constitution, use in lending, staking, and DeFi, and appeal to users who prefer community-governed, non-custodial systems.
Meme Coins and Risk
Dogecoin is a decentralized, open-source cryptocurrency created in 2013 as a simple and accessible alternative to Bitcoin. It became widely known as an original meme coin and experienced major growth in 2020 and 2021.
Aalto Investment Club described it as beginning as a joke and said its growth showed that a project's price can move independently of traditional fundamental analysis. The article stated that it was debatable whether buying early meme-coin trends constituted investing or gambling.
A commenter in the White Coat Investor discussion cited Fartcoin as an example of a meme coin that reportedly rose to an $800 million market capitalization after a presidential election. Another commenter claimed that many meme coins were promoted by insiders controlling a large share of supply, after which the price could be pumped on social media and distributed to holders through a pump-and-dump pattern. These were presented as market observations, not as a verified assessment of every meme coin.
Meme-coin risks described or implied across the materials include:
Meme coin risks
- Low or unpredictable utility
- Concentrated insider holdings
- Artificial social-media promotion
- Sudden liquidity loss
- Pump-and-dump activity
- Difficulty selling after a price decline
- Low market capitalization
- Dependence on a small number of wallets
- Use of a famous name or theme without an established development history
- High volatility and limited fundamental value
A meme coin can produce substantial gains, but those gains do not establish a working product, durable cash flow, or reliable long-term value.
Portfolio Approaches
The source material presents several distinct portfolio philosophies.
Small Fixed Allocation - A 2% allocation with 1.6% and 2.5% rebalancing thresholds was used to control volatility, FOMO, and disruption to the rest of the portfolio.
Play-Fund Limit - A February 2022 adviser suggested treating crypto as spending money and limiting it to 5% of net worth so a failure would not damage savings goals.
Approximately 5% Speculative Allocation - A White Coat Investor author later described approximately 5% as a level for a believer in bitcoin. The intended outcome was to make a successful investment meaningful without allowing a failure to destroy a reasonable financial plan.
No Allocation - Some participants in the White Coat Investor comments did not include bitcoin because they could not identify a present use or could not justify owning a non-producing asset based only on an expected price increase.
Established Assets First - The June 2026 CoinCodex project article recommended Bitcoin and Ethereum for long-term investors, describing their ecosystems and fundamentals as more robust than projects dependent on a few developers. It still classified both as risky.
Specialized or High-Risk Assets - The same article included newer decentralized-trading, AI, privacy, Bitcoin-layer, and tokenization projects for readers able to evaluate their technology and token systems. It separated these from its beginner-oriented examples of Bitcoin, Ethereum, Litecoin, Polygon, and Solana.
Active Trading or Holding - Trading requires attention to entries, exits, fees, spreads, and price movements. Holding reduces transaction frequency but exposes the asset to long-term declines. Rebalancing can manage volatility but may reduce upside and trigger taxes.
The sources did not identify one approach as universally correct. The approaches differ in time horizon, expected return, asset utility, loss tolerance, portfolio purpose, and willingness to monitor the investment.
Tax and Due Diligence
Heather Townsend noted in February 2022 that buying, selling, and spending cryptocurrency could be a taxable event and had to be reported. She wrote that the IRS had placed a cryptocurrency question on the first page of the tax return. Tax rules can change, and a sale, swap, payment, staking reward, liquidity event, or reward from an airdrop may be treated differently from simply holding an asset.
The WazirX FAQ gave India-specific information and described the legal situation as legal but lacking a comprehensive regulatory framework. It stated that companies may need to record crypto transactions and that gains could be taxable for Indian tax residents or assets domiciled in India.
It also gave a historical timeline:
India crypto legal timeline
- In April 2018, the Reserve Bank of India advised organizations under its jurisdiction not to trade in virtual currencies or provide services for settling them.
- In 2019, a government committee proposed outlawing private cryptocurrencies and imposing penalties.
- In March 2020, the Supreme Court overruled the RBI circular, allowing banks to work with cryptocurrency dealers and exchanges.
Those statements were presented in a FAQ and may not describe the complete current legal framework. Tax and legal treatment varies by country and can change through new legislation, court decisions, tax guidance, and exchange-reporting rules.
Safety and Scams
The sources repeatedly warned against relying on social-media rumors, guaranteed returns, or unexplained presales. A balanced research process should identify:
Due diligence checklist
- The project's legal entity and founders
- The token contract and blockchain
- Whether the token is mintable, burnable, pausable, upgradeable, or controlled by an administrator
- How much supply is held by insiders
- Whether vesting schedules are disclosed
- Whether liquidity is locked and whether a lock can be bypassed
- Whether audits were independent and current
- Whether a wallet can be upgraded or drained
- Whether the project can print more tokens
- Whether a presale has refund or vesting terms
- Whether an airdrop requires a seed phrase or excessive permissions
- Whether yield comes from fees, emissions, borrowing, subsidies, or another source
- Whether a stablecoin's reserves are redeemable
- Whether an exchange holds assets in custody and what protections apply
- Whether an influencer is being compensated
- Whether profit claims are realistic and documented
The Aalto Investment Club disclaimer stated that nothing in its material should be treated as investment advice, that no project or company was endorsed, and that readers should invest only money they could afford to lose. CoinCodex similarly warned that cryptocurrency is risky and volatile even for established assets.
Some smart people will figure out some useful things with crypto, and I do not want my Fear of Missing Out to affect other aspects of my financial plan.
This was Francis Bayes, a White Coat Investor columnist, writing his crypto investment thesis in 2021. He said the first part of the thesis had not developed as expected because people had also used crypto to scam others. He continued to hold because he did not want fear of missing out to damage other parts of his plan.
His allocation at the time was 98% stocks, all held in index funds, and 2% crypto. He described 1% to 5% as a range he considered reasonable for exploiting volatility and possibly reducing portfolio correlation with stocks. He considered the difference between 1% and 2% negligible for the overall portfolio, while moving from 2% to 5% would add meaningful risk and emotional pressure. This was his personal allocation, not a universal recommendation.
Bayes rebalanced stocks annually using new contributions to retirement accounts. Crypto was handled more actively: he bought when crypto reached 0.8 times the target allocation, equal to 1.6% of the portfolio, and sold when crypto reached 1.25 times the target allocation, equal to 2.5%. Proceeds from crypto sales went into stocks. Crypto purchases came from cash in his checking account.
He wrote the thresholds into a plan and used conditional formatting in Google Sheets or Microsoft Excel to change a cell color when the crypto allocation moved outside the target range.
Behavioral discipline did not remove the difficulty of following the plan. Instead of buying a large lump sum during the summer 2022 crash, Bayes bought in small amounts because he feared another decline. When crypto exceeded 2.5% in fall 2024, he did not sell at Bitcoin prices of $90,000, $95,000, or $98,000 because he feared missing further gains. He eventually sold the excess while writing about the need to practice his own plan.
A commenter asked why proceeds were not used to buy more index funds rather than being held as cash. Bayes explained that he preferred to use checking cash for the taxable stock purchase because he had other near-term uses for the cash, and he wanted to take gains before a possible crash. He also noted that his exchange charged no transaction fee but did charge a spread. Another commenter suggested that buying more index funds with new cash could be a useful future behavior.
Bayes calculated the annualized real return of the crypto portion of his portfolio to understand its volatility and contribution. Before 2024, crypto had reduced the portfolio's annualized real return. The reported effects were: crypto reduced the portfolio's 2022 return by 1.05%, improved the portfolio's 2023 return by 0.88%, and from 2021 through 2023, crypto reduced the portfolio's overall annualized real return by 0.09%.
In 2024, the crypto position produced a 91% real return despite the sale of some Bitcoin for rebalancing. The allocation did not exceed 3% during the year. Crypto improved the total portfolio's return by 1.29%, and from 2021 through 2024 it improved the portfolio's overall annualized real return by 0.22%.
Bayes described crypto's positive portfolio contribution as a secondary benefit. His main reason for including it was to avoid interrupting the compounding of the other 98% of his portfolio. He referred to Charlie Munger's first rule of compounding: do not interrupt compounding unnecessarily. Munger had also called crypto "rat poison," creating a contrast between that warning and Bayes's small, planned allocation.
The application to crypto was straightforward: Bitcoin's price should not be the sole reason to buy it. Someone who buys because the price has already risen may be more likely to sell after a decline. A person who buys because the price has fallen may be afraid that it will fall further. The investment thesis, target allocation, liquidity needs, and time horizon matter more than the current quote.
One commenter suggested investing 2% of savings each year in Bitcoin without rebalancing, particularly if Bitcoin was expected to outperform the S&P 500 by a wide margin. Another view was that a 2% allocation is already so small that it may not materially change long-term wealth. White Coat Investor responses emphasized the difficulty of forecasting returns, the possibility that Bitcoin could be replaced by another technology, and the possibility that an asset might level off or lose value.
The source material did not resolve whether rebalancing or holding without rebalancing was superior. Both approaches were presented as dependent on assumptions about future returns, volatility, taxes, and loss tolerance.
Competing Views on Bitcoin
Supporters of bitcoin described it as a secure store of value with a fixed supply. They cited the following properties: transactions can operate 24/7, Bitcoin can be sent globally without a conventional intermediary, the supply has a fixed cap of 21 million, Bitcoin can be divided into very small units, it can be held without dependence on a bank, users can control private keys and self-custody, its monetary policy cannot be expanded by a government in the same way as fiat currency, it can be transferred globally with low friction, and it is available through many exchanges and trading pairs.
A commenter described Bitcoin as "the world's most liquid asset" and said it could be bought or sold around the clock. Other comments argued that it was faster to transfer internationally than conventional banking rails and that its fixed cap made it different from fiat currencies, gold, and real estate.
Supporters also compared bitcoin's growth with other technologies. They described adoption as moving from a niche experiment toward a multi-trillion-dollar asset, with ETFs, institutional interest, national discussion, mining, payment experiments, and broader public awareness. One commenter stated that bitcoin had reached a $2 trillion market capitalization and described its path from an asset with little value to one larger than most national economies and many companies. These were advocacy claims rather than guarantees.
Skeptics argued that bitcoin still had limited practical use for ordinary legal transactions in the United States. They contrasted its properties with assets that produce income: stocks represent earnings, bonds pay interest, real estate can produce rent, and Bitcoin does not automatically produce cash flow. They also questioned whether future adoption would occur. Bitcoin proponents had predicted widespread payment use for more than a decade, but bitcoin was still not commonly used for groceries, rent, payroll, or everyday purchases in many countries.
Other concerns included: Bitcoin has a much shorter history than gold, real estate, or cash; past returns can attract buyers for the wrong reason; a large market capitalization has not necessarily reduced volatility; a network may remain valuable without being widely used as everyday money; self-custody can be technically difficult, and a hardware wallet or seed phrase can still be lost or compromised; a private key may reduce confiscation risk, but physical coercion, seizure, legal restrictions, or threats can still affect ownership; Bitcoin could continue to rise, remain flat, decline, or lose most of its value; a successful future for bitcoin would not guarantee that every price forecast or entry point was correct; and past growth from a very low starting value could not safely be projected forward indefinitely.
A White Coat Investor response calculated that bitcoin had risen from approximately $0.30 in 2011 to $94,420 in early January 2025, equivalent to about 147% annualized. The response argued that repeating that rate would produce implausibly large future values: approximately $4 million per bitcoin in four years, or a total value comparable to the world's net worth within six years. The point was that extraordinary historical growth should not be treated as a normal expected return.
The same response stated that $4 million could be possible if bitcoin became the world's sole currency, but that $10 million in today's dollars appeared highly unlikely. It also stated that a long-term investor would need to decide how much lifetime savings could be exposed to that outcome. The author said he would consider approximately 5% for someone who genuinely believed in bitcoin and understood the risk. That was presented as a discussion of sizing, not a prediction.
The White Coat Investor author's criteria for including an asset in a portfolio were: it produces earnings, interest, rent, or another form of economic output; it has a track record of at least hundreds of years; and it does not have a large following that the author regarded as religious or gambling-oriented.
Bitcoin Staking and Layer 2
Stacks is a smart-contract and application layer for Bitcoin. Its blocks are anchored to Bitcoin without requiring changes to Bitcoin itself. After the Nakamoto upgrade in October 2024, Stacks introduced faster block times and Bitcoin finality for confirmed transactions.
The network uses Proof of Transfer. Miners spend BTC to produce Stacks blocks, and STX holders can earn BTC through a process called stacking. Stacks also supports sBTC, a 1:1 Bitcoin-backed asset for use in decentralized applications. Its Clarity smart-contract language is designed to make contract behavior more transparent and predictable.
A Stacks whitepaper described a self-custodial mechanism intended to let Bitcoin holders earn Bitcoin-denominated yield while keeping BTC locked on Bitcoin under their own keys. The proposed structure paired a six-month timelock lock for BTC on Bitcoin with an STX lock on Stacks, rewards paid in BTC by Stacks miners, and distribution of excess rewards to STX-only stakers and a reserve fund.
The stated purpose was to allow treasury managers and institutions to earn yield without surrendering custody, lending BTC, moving it off-chain, or relying on a wrapper or bridge. UTXO Management was announced as an inaugural participant.
The proposed feature was expected on the Stacks mainnet later in 2026. The yield would come from BTC paid by Stacks miners rather than from an unrelated external source. The design still depends on smart contracts, economic incentives, protocol security, and the continued value of STX and BTC.
Other Notable Projects
Zcash - Zcash was proposed in a 2014 publication titled "Zerocash" and launched in 2016. It is a decentralized public peer-to-peer cryptocurrency with privacy features based on zero-knowledge proofs. Zcash was the first cryptocurrency to use zk-SNARKs, a zero-knowledge protocol included by MIT Technology Review among its top ten technological breakthroughs of 2018. It uses proof of work and has the same 21 million total supply cap introduced by Bitcoin. Its first halving occurred at block height 1,046,400 in 2020.
Zcash reportedly rose from $425 to $532 in one day after a vulnerability disclosure. The same period included a fall from $630 to $263 after disclosure of a vulnerability that could have allowed an attacker to create an unlimited number of shielded ZEC in the Orchard privacy pool. The Ironwood upgrade was described as a way to verify that no counterfeit ZEC had been minted.
Hyperliquid - Hyperliquid is a Layer 1 blockchain designed for decentralized trading. It is described as handling around 100,000 orders per second with low fees and low slippage. Its order book is intended to provide a user experience similar to a centralized exchange. The platform supports many crypto assets, copy trading, and leverage of up to 50 times on selected trading pairs.
The HYPE token was distributed through an airdrop to more than 90,000 users in November 2024. The source associated the positive response with broad token distribution and the absence of venture-capital involvement. The total supply is capped at 1 billion HYPE, with more than 76% allocated to the user community.
Jeffrey Sprecher, founder of the NYSE and CEO of Intercontinental Exchange, was quoted describing Hyperliquid as larger than Nasdaq and noting that it operated with a small team. He also said the exchange's founders were "extremely smart" and that its 24/7 trading, including weekend oil derivatives, demonstrated demand for always-on markets.
Leverage of up to 50 times can magnify gains and losses. Decentralization does not eliminate smart-contract, validator, market-liquidity, liquidation, or counterparty risk.
Solana - Solana is a high-performance smart-contract platform founded by Anatoly Yakovenko in 2018. Its mainnet launched in March 2020. Solana combines a Proof-of-History mechanism with proof of stake. The network is designed to process thousands of transactions per second at low cost. The article said SOL transfers often cost less than $0.001.
South Korea's Shinhan Card, described as the country's largest card issuer, partnered with the Solana Foundation to test stablecoin payments for its 28 million cardholders. The proof of concept was to examine payments between customers and merchants on Solana's testnet. Non-custodial wallet security is a major deployment condition.
Solana-based tokenized real-world assets were reported to have passed $2.5 billion for the first time. Solana developers were also working on post-quantum security because quantum computing could threaten existing digital-signature systems.
NEAR Protocol - NEAR Protocol is a high-throughput blockchain built around sharding. It emphasizes rapid finality, scalable execution, private computation, and applications related to artificial intelligence. Smart contracts can be written in Rust and JavaScript. Contract developers receive 30% of the gas fees burned when their contracts are used.
NEAR Intents is a multichain transaction framework in which a user states a desired result and independent parties compete to fulfill it. A common use is swapping assets across networks without manually choosing every step. A dynamic resharding upgrade scheduled for June 2026 was intended to let the network add capacity automatically as usage increased.
Bittensor - Bittensor is a decentralized peer-to-peer market for machine intelligence. The network is divided into specialized subnets for tasks such as text prompting, transcription, image generation, or audio generation. Bittensor uses Yuma Consensus. Miners provide machine-learning computing resources, validators evaluate work, and TAO tokens reward and pay for those services.
Subnet 3, called Templar, released Covenant-72B, a large language model trained across more than 70 contributors. The model was trained on 1.1 trillion tokens and received an MMLU score of 67.1. The article compared that scale with Meta's Llama 2 70B.
Sky - Sky is a decentralized-finance protocol that issues USDS, a stablecoin intended to track the U.S. dollar. Users can lock collateral such as ETH into smart contracts and mint USDS against it. The system is overcollateralized: the collateral must be worth more than the minted stablecoin, and a position can be liquidated if its collateral value falls. Sky began under the name Maker in 2014, and its original stablecoin, Dai, launched in late 2017.
The article reported that Sky generated $338 million in protocol revenue in 2025, increased USDS supply by 74% year over year to $9.2 billion, reduced quarterly core operating expenses by 63% year over year to $8.8 million, maintained more than $4 billion in instant-redemption liquidity through its Peg Stability Module, supported zero-slippage swaps between USDC and USDS, increased holders from 509,000 to 582,000, and saw the Sky Savings Rate decline from 12.5% to 4% as DeFi rates compressed.
Stellar - Stellar focuses on payments and asset tokenization. It was founded by Joyce Kim and Jed McCaleb, who had also been involved in XRP. Stellar uses the Stellar Consensus Protocol, which is neither proof of work nor proof of stake. The minimum transaction fee is 0.00001 XLM, although the article said users would commonly pay around 0.0001 XLM. Stellar includes a built-in decentralized exchange for assets issued on the network. Soroban is its smart-contract platform.
XLM was reported to have risen 72% in seven days after the Depository Trust & Clearing Corporation announced plans to enable tokenization of DTC-custodied assets on Stellar. The assets were expected to become available on Stellar in the first half of 2027. The integration covers the lifecycle of tokenized assets, including issuance, corporate actions, reporting, conversion, and settlement.
BNB - BNB was launched by Binance in 2017. It has two principal functions: a utility and governance asset within the Binance ecosystem, and the native asset used to pay transaction costs on BNB Chain. BNB holders can receive reduced trading fees and access Binance products such as Launchpad, Launchpool, and card cashback. BNB Chain is an Ethereum-compatible network with lower fees and supports EVM-compatible decentralized applications.
The 33rd quarterly BNB burn removed 1.44 million BNB, reported as worth approximately $12 billion at the time. The burn reduced supply to 137.7 million BNB. BNB's auto-burn mechanism considers the token price and the number of blocks produced during the quarter. The stated supply target was 100 million BNB.
BNB was reported as rising 20.6% against the U.S. dollar over 30 days, compared with Bitcoin at 5.2% and Ethereum at 3.8%. A Coinbase listing was described as notable because Binance remained BNB's central ecosystem while also competing with Coinbase. The article characterized the listing as a possible sign of a more favorable regulatory environment, while noting that BNB had previously faced securities-law controversy because it was created and sold by Binance.
Burns reduce supply according to the mechanism, but token value can still decline. Exchange dependence, regulatory treatment, smart-contract risk, governance concentration, and network usage affect the investment case.
Reading Crypto News and Blogs
Crypto blogs can provide current market context, but the quality of information depends on the author, evidence, transparency, and incentives.
Prices can react to regulation, hacking incidents, exchange failures, project launches, token unlocks, governance votes, security disclosures, corporate treasury purchases, ETF flows, interest rates, geopolitical events, and changes in market sentiment. A project that remains technologically unchanged can still experience a major price move.
Crypto blogs can explain blockchain terminology, summarize long technical documents, track exchange and project developments, provide beginner guides, compare wallets, protocols, and token models, explain regulatory and security events, present market analysis, identify whitepapers, governance proposals, and development activity, provide context for token unlocks, listings, and network use, and help readers compare multiple interpretations of the same event.
Social media can provide speed, but it can also contain rumors, coordinated promotion, manipulated screenshots, and incomplete information. Reading several sources is presented as a way to compare viewpoints.
Types of crypto blogs include news blogs, trading blogs, educational blogs, community blogs, project-update blogs, tokenization blogs, security blogs, and regulatory blogs.
A source can be evaluated using the following questions: Are the author's qualifications and identity clear? Does the author disclose financial interests, sponsorships, or token holdings? Are claims linked to primary documents, official announcements, on-chain data, or other verifiable evidence? Are price predictions distinguished from established facts? Are risks and adverse scenarios explained? Are token promotions presented as editorial coverage or advertising? Does the source correct errors? Are data dates and time zones disclosed? Does the source avoid guaranteed-return language? Are security claims supported by formal audits or only by the project's own statement? Does the content provide balanced treatment rather than only bullish or bearish claims? Are references to "top," "best," or "trusted" based on disclosed criteria?
Readers can use website alerts, newsletters, X, Facebook, YouTube, Telegram, Reddit, or other social channels, forums, exchange announcements, governance forums, on-chain dashboards, official project blogs, regulatory-agency publications, and academic and technical research. Different analysts can interpret the same event differently. Comparing multiple sources can show whether a claim is broadly supported or driven by one interpretation.
Comparing Different Lists
The sources used different approaches to choosing crypto:
Different list approaches
- A January 2025 personal portfolio example used a 2% crypto allocation.
- A February 2022 adviser recommended no more than 5% of net worth in a play fund.
- A White Coat Investor site owner said he would generally suggest approximately 5% for someone convinced about bitcoin.
- A June 2026 project-ranking article emphasized Bitcoin and Ethereum for long-term investors while including several higher-risk specialized networks.
- The same June 2026 article said an investor with a greater risk appetite could consider assets below one cent or new presales, while warning that crypto is highly volatile.
- A December 2025 stablecoin list focused on tokens designed to track dollars or gold rather than on high-growth protocols.
- Meme-coin commentary treated meme coins as a distinct and much higher-risk category.
These lists were not presented as permanent rankings. Prices, market capitalizations, exchange listings, regulations, and project conditions change.
Final Thoughts on Investing in Crypto
If you're thinking about how to invest in a crypto coin, start with what it is and how it's used. Look at Bitcoin, stablecoins, and the projects that interest you. Compare how easily it can be bought or sold, what technology it uses, and how its token system works.
The sources repeatedly emphasize that the decision should be based on a personal plan rather than the current Bitcoin price. Identify the amount that can be lost without disrupting savings or other goals before buying. Smaller, newer tokens can produce larger gains but can also lose most or all of their value.
A 2% allocation with 1.6% and 2.5% rebalancing thresholds was used to control volatility, FOMO, and disruption to the rest of the portfolio. A financial adviser's recommendation was no more than 5% of net worth in a play fund. A White Coat Investor author later suggested approximately 5% for a convinced bitcoin believer. These figures show differing personal boundaries rather than a single settled standard.
Crypto can be treated as one part of a diversified allocation rather than as the entire portfolio. The 98% stock and 2% crypto example was intended to keep crypto from affecting cash flow or disrupting the compounding of the main portfolio.
Rather than investing one large sum at a specific moment, an investor can purchase smaller amounts over time. Bayes said he might use dollar-cost averaging while prices were falling and generally did not rebalance more than one or two times per year. These approaches require assumptions about future returns and can perform differently if an asset rises or falls rapidly.
A written rebalancing rule can specify the target allocation, the lower threshold for buying, the upper threshold for selling, which account supplies cash, which asset receives sale proceeds, how taxes and transaction costs are considered, and what happens if the asset becomes impaired or loses most of its value.
Heather Townsend advised clients who had gains they would hate to lose to consider taking some gains off the table. She noted that several clients who followed similar advice while bitcoin was in the $60,000s felt better about subsequent volatility when bitcoin later moved into the $30,000s.
The Aalto Investment Club disclaimer stated that nothing in its material should be treated as investment advice, that no project or company was endorsed, and that readers should invest only money they could afford to lose. CoinCodex similarly warned that cryptocurrency is risky and volatile even for established assets.
Crypto blogs can provide current market context, but the quality of information depends on the author, evidence, transparency, and incentives. Prices can react to regulation, hacking incidents, exchange failures, project launches, token unlocks, governance votes, security disclosures, corporate treasury purchases, ETF flows, interest rates, geopolitical events, and changes in market sentiment.
The sources repeatedly warned against relying on social-media rumors, guaranteed returns, or unexplained presales. A balanced research process should identify the project's legal entity and founders, the token contract and blockchain, whether the token is mintable, burnable, pausable, upgradeable, or controlled by an administrator, how much supply is held by insiders, whether vesting schedules are disclosed, whether liquidity is locked and whether a lock can be bypassed, whether audits were independent and current, whether a wallet can be upgraded or drained, whether the project can print more tokens, whether a presale has refund or vesting terms, whether an airdrop requires a seed phrase or excessive permissions, whether yield comes from fees, emissions, borrowing, subsidies, or another source, whether a stablecoin's reserves are redeemable, whether an exchange holds assets in custody and what protections apply, whether an influencer is being compensated, and whether profit claims are realistic and documented.
Different portfolio philosophies include small fixed allocation, play-fund limit, approximately 5% speculative allocation, no allocation, established assets first, specialized or high-risk assets, and active trading or holding. The sources did not identify one approach as universally correct. The approaches differ in time horizon, expected return, asset utility, loss tolerance, portfolio purpose, and willingness to monitor the investment.
Trees don't grow to the sky.
A White Coat Investor response used this phrase to warn against extrapolating extraordinary early returns. The response estimated that if Bitcoin replaced approximately $80 trillion of the world's money, rose from an approximately $2 trillion market capitalization to that level, and then returned only an inflation-like rate, the remaining upside would be finite. The calculation was presented as a reason to be skeptical of unlimited future returns, not as a price forecast.
The same response stated that $4 million could be possible if bitcoin became the world's sole currency, but that $10 million in today's dollars appeared highly unlikely. It also stated that a long-term investor would need to decide how much lifetime savings could be exposed to that outcome. The author said he would consider approximately 5% for someone who genuinely believed in bitcoin and understood the risk. That was presented as a discussion of sizing, not a prediction.
Bitcoin supporters frequently compared it with gold. A commenter argued that gold's nominal price increased because dollars lost purchasing power. The comparison used a 1978 gold price of about $193 per ounce and a later price near $2,680 per ounce. The commenter calculated a 5.6% compound annual growth rate, then added an estimated 1.8% annual increase in mined gold supply to arrive at a 7.4% rate comparable to monetary-supply expansion.
Gold supporters responded that gold, art, collectibles, watches, real estate, and stocks also derive much of their value from what other people are willing to pay. Critics of bitcoin argued that its market capitalization and recent adoption do not prove it will capture a large monetary premium.
Some supporters characterized bitcoin as uncensorable and unconfiscatable because a user who controls the private key can transfer it without asking another institution for permission. Critics replied that "less confiscatable" may be more accurate than "unconfiscatable." Government seizure, coercion, inheritance disputes, compromised keys, and physical threats can still affect ownership.
Supporters also cited self-custody as a way to reduce dependence on exchanges. Critics emphasized that self-custody transfers responsibility to the owner and creates risks when software, hardware, passwords, recovery phrases, or backups are handled incorrectly. A well-established exchange may be more convenient for recurring purchases, while a hardware wallet may provide stronger control after purchase.
One commenter stated that El Salvador had made bitcoin legal tender and that businesses there accepted it. Other comments said payment use remained limited, although Lightning Network payments, gift cards, bars, and other experiments existed. U.S. capital-gains treatment was described as a reason bitcoin holders might prefer to hold rather than spend.
A commenter said Russian foreign transactions were being conducted with bitcoin, but this was presented as commentary rather than a developed use-case analysis. Other comments referred to possible national strategic bitcoin reserves and to proposed U.S. adoption. The existence or size of such a reserve was not established by the investment case itself.
Comments also noted that bitcoin had reached a $2 trillion market capitalization in roughly 16 years, was mined without a company CEO or marketing department, and had developed a substantial market. Skeptics replied that adoption predictions had repeatedly been premature. They also cited multiple "crypto winters," when public attention disappeared after prices fell.
Supporters of bitcoin described it as a secure store of value with a fixed supply. They cited properties including: transactions can operate 24/7, Bitcoin can be sent globally without a conventional intermediary, the supply has a fixed cap of 21 million, Bitcoin can be divided into very small units, it can be held without dependence on a bank, users can control private keys and self-custody, its monetary policy cannot be expanded by a government in the same way as fiat currency, it can be transferred globally with low friction, and it is available through many exchanges and trading pairs.
Skeptics argued that bitcoin still had limited practical use for ordinary legal transactions in the United States. They contrasted its properties with assets that produce income: stocks represent earnings, bonds pay interest, real estate can produce rent, and Bitcoin does not automatically produce cash flow. They also questioned whether future adoption would occur.
Bitcoin proponents had predicted widespread payment use for more than a decade, but bitcoin was still not commonly used for groceries, rent, payroll, or everyday purchases in many countries. The possibility remained that another cryptocurrency, existing fiat currency, bank ledger, or payment network could dominate future use.
Other concerns included: Bitcoin has a much shorter history than gold, real estate, or cash; past returns can attract buyers for the wrong reason; a large market capitalization has not necessarily reduced volatility; a network may remain valuable without being widely used as everyday money; self-custody can be technically difficult, and a hardware wallet or seed phrase can still be lost or compromised; a private key may reduce confiscation risk, but physical coercion, seizure, legal restrictions, or threats can still affect ownership; Bitcoin could continue to rise, remain flat, decline, or lose most of its value; a successful future for bitcoin would not guarantee that every price forecast or entry point was correct; and past growth from a very low starting value could not safely be projected forward indefinitely.
One commenter suggested investing 2% of savings each year in Bitcoin without rebalancing, particularly if Bitcoin was expected to outperform the S&P 500 by a wide margin. Another view was that a 2% allocation is already so small that it may not materially change long-term wealth. White Coat Investor responses emphasized the difficulty of forecasting returns, the possibility that Bitcoin could be replaced by another technology, and the possibility that an asset might level off or lose value.
The source material did not resolve whether rebalancing or holding without rebalancing was superior. Both approaches were presented as dependent on assumptions about future returns, volatility, taxes, and loss tolerance.
Bayes described crypto's positive portfolio contribution as a secondary benefit. His main reason for including it was to avoid interrupting the compounding of the other 98% of his portfolio. He referred to Charlie Munger's first rule of compounding: do not interrupt compounding unnecessarily. Munger had also called crypto "rat poison," creating a contrast between that warning and Bayes's small, planned allocation.
The application to crypto was straightforward: Bitcoin's price should not be the sole reason to buy it. Someone who buys because the price has already risen may be more likely to sell after a decline. A person who buys because the price has fallen may be afraid that it will fall further. The investment thesis, target allocation, liquidity needs, and time horizon matter more than the current quote.
One commenter suggested investing 2% of savings each year in Bitcoin without rebalancing, particularly if Bitcoin was expected to outperform the S&P 500 by a wide margin. Another view was that a 2% allocation is already so small that it may not materially change long-term wealth. White Coat Investor responses emphasized the difficulty of forecasting returns, the possibility that Bitcoin could be replaced by another technology, and the possibility that an asset might level off or lose value.
The source material did not resolve whether rebalancing or holding without rebalancing was superior. Both approaches were presented as dependent on assumptions about future returns, volatility, taxes, and loss tolerance.
Bayes calculated the annualized real return of the crypto portion of his portfolio to understand its volatility and contribution. Before 2024, crypto had reduced the portfolio's annualized real return. The reported effects were: crypto reduced the portfolio's 2022 return by 1.05%, improved the portfolio's 2023 return by 0.88%, and from 2021 through 2023, crypto reduced the portfolio's overall annualized real return by 0.09%.
In 2024, the crypto position produced a 91% real return despite the sale of some Bitcoin for rebalancing. The allocation did not exceed 3% during the year. Crypto improved the total portfolio's return by 1.29%, and from 2021 through 2024 it improved the portfolio's overall annualized real return by 0.22%.
Bayes cautioned that this result should not be extrapolated across future decades. A 91% or 120% annual gain is not the same as a sustainable long-term return, and a mature asset class may not repeat several early crypto cycles.
Relative to a baseline projection of a 5% real portfolio return, a 0.22 percentage-point annualized improvement over 30 years would produce approximately $2,800 more for every $10,000 invested.
The personal example illustrates several recurring issues: a written target can define when to buy and sell, dollar-cost averaging can reduce the timing of a large purchase, a cash account can supply new contributions without selling other assets, crypto gains can be rebalanced into stocks, rebalancing can reduce a concentrated position after a price surge, active rebalancing carries its own risk if the asset later falls toward zero, tax-account location can affect which assets can be held and where purchases can be funded, and an investor may follow the target intellectually but still struggle to act because of fear or greed.
A commenter asked why proceeds were not used to buy more index funds rather than being held as cash. Bayes explained that he preferred to use checking cash for the taxable stock purchase because he had other near-term uses for the cash, and he wanted to take gains before a possible crash. He also noted that his exchange charged no transaction fee but did charge a spread. Another commenter suggested that buying more index funds with new cash could be a useful future behavior.
Francis Bayes wrote a crypto investment thesis in 2021: "Some smart people will figure out some useful things with crypto, and I do not want my Fear of Missing Out to affect other aspects of my financial plan." He said the first part of the thesis had not developed as expected because people had also used crypto to scam others. He continued to hold because he did not want fear of missing out to damage other parts of his plan.
His allocation at the time was 98% stocks, all held in index funds, and 2% crypto. He described 1% to 5% as a range he considered reasonable for exploiting volatility and possibly reducing portfolio correlation with stocks. He considered the difference between 1% and 2% negligible for the overall portfolio, while moving from 2% to 5% would add meaningful risk and emotional pressure. This was his personal allocation, not a universal recommendation.
Bayes rebalanced stocks annually using new contributions to retirement accounts. Crypto was handled more actively: he bought when crypto reached 0.8 times the target allocation, equal to 1.6% of the portfolio, and sold when crypto reached 1.25 times the target allocation, equal to 2.5%. Proceeds from crypto sales went into stocks. Crypto purchases came from cash in his checking account.
He wrote the thresholds into a plan and used conditional formatting in Google Sheets or Microsoft Excel to change a cell color when the crypto allocation moved outside the target range.
Behavioral discipline did not remove the difficulty of following the plan. Instead of buying a large lump sum during the summer 2022 crash, Bayes bought in small amounts because he feared another decline. When crypto exceeded 2.5% in fall 2024, he did not sell at Bitcoin prices of $90,000, $95,000, or $98,000 because he feared missing further gains. He eventually sold the excess while writing about the need to practice his own plan.
A commenter asked why proceeds were not used to buy more index funds rather than being held as cash. Bayes explained that he preferred to use checking cash for the taxable stock purchase because he had other near-term uses for the cash, and he wanted to take gains before a possible crash. He also noted that his exchange charged no transaction fee but did charge a spread. Another commenter suggested that buying more index funds with new cash could be a useful future behavior.
Heather Townsend's January 2022 view was that she had not found evidence-based research supporting crypto allocation to client portfolios and that its risk-to-reward ratio did not meet her criteria. She compared it with the dot-com bubble and questioned whether projects such as Pets.com and theGlobe.com would survive. She also stated that governments might develop their own digital currencies rather than adopt Bitcoin, Ether, or Dogecoin.
Her conclusion was that crypto might remain, but investors who participate should treat it as a limited "play fund," keep it separate from other savings goals, and invest no more than 5% of net worth. That limit was specific to her February 2022 article and was not presented as a universal threshold.
At the end of January 2022, Townsend Financial described the overall crypto market as down 7% and Bitcoin as down 20% for that year. The comparison was specific to that date.
Bitcoin rose more than 120% in 2024. In December 2024, it traded above $90,000 and then surpassed $100,000 a few days later. Those figures describe calendar-year or point-in-time performance and do not represent the return of every investor. A personal portfolio can experience a different result because of purchase dates, rebalancing, taxes, fees, and the amount allocated.
A June 2026 CoinCodex page displayed a broader market snapshot of total crypto market capitalization at $2.22 trillion, down 1.66%, Bitcoin dominance at 58.36%, down 0.26%, 24-hour crypto volume at $356.97 billion, up 21.22%, Bitcoin at $64,553, down 2.05%, S&P 500 at 7,421.76, down 1.21%, Gold at $4,320.95, down 0.44%, and USD/EUR at €0.87, up 0.82%.
The same page gave Bitcoin's price as $66,150 in its Bitcoin section, while a later data table listed a $1.33 trillion Bitcoin market capitalization. The page's global snapshot showed a $2.22 trillion total crypto market rather than a Bitcoin-only value. These figures were captured at different points or in different components of the page and should be treated as time-sensitive snapshots rather than permanently fixed values.
The CoinCodex article said Bitcoin had recovered from a June 6 low of $59,000. Geoffrey Kendrick of Standard Chartered was quoted describing $59,000 as the bottom of the current cycle and expecting Bitcoin to reach $100,000 and Ether to reach $4,000 by year-end. The article also cited more than $5.72 billion in outflows from spot bitcoin ETFs since the second week of May, anecdotal claims that some ETF investors were selling to raise money for a SpaceX IPO, a need for U.S. spot bitcoin ETF flows to return to positive net daily inflows, a planned U.S.-Iran peace agreement expected to reduce geopolitical uncertainty, lower oil prices and expectations of lower Treasury yields, potentially supporting risk assets, and Michael Saylor announcing that Strategy had purchased 1,587 BTC for $100 million at an average price of $63,024.
Institutional accumulation, ETF flows, government policy, geopolitical developments, and large corporate purchases can influence market expectations. The listed events do not establish a guaranteed future price.
CoinCodex identified Bitcoin as the leading cryptocurrency by market capitalization and listed it as a decentralized peer-to-peer cryptocurrency. Its June 15, 2026 data table reported a Bitcoin market capitalization of $1.33 trillion. The page's price ticker showed $64,553 at one point, while the Bitcoin section quoted $66,150 after a reported 4.5% seven-day increase.
Bitcoin is a decentralized peer-to-peer cryptocurrency introduced in 2008 and launched in early 2009. It introduced the blockchain model, uses proof of work, and rewards miners who add blocks. Its fixed issuance schedule is designed to limit supply to 21 million BTC.
Bitcoin transactions can be sent at any time and can be settled without a bank. Users can hold their own private keys and self-custody rather than relying on an exchange. The network's open transaction history and proof-of-work sequence make altering recorded transactions extremely difficult.
Zcash was proposed in a 2014 publication titled "Zerocash" and launched in 2016. It is a decentralized public peer-to-peer cryptocurrency with privacy features based on zero-knowledge proofs. Zcash was the first cryptocurrency to use zk-SNARKs, a zero-knowledge protocol included by MIT Technology Review among its top ten technological breakthroughs of 2018. It uses proof of work and has the same 21 million total supply cap introduced by Bitcoin. Its first halving occurred at block height 1,046,400 in 2020. Developers and much of the Zcash community were described as supportive of a possible future transition to proof of stake.
CoinCodex listed Zcash with ticker ZEC, launch 2016, market capitalization on June 15, 2026 at $8.8 billion, and function as privacy coin based on zero-knowledge technology.
Hyperliquid is a Layer 1 blockchain designed for decentralized trading. It is described as handling around 100,000 orders per second with low fees and low slippage. Its order book is intended to provide a user experience similar to a centralized exchange. The platform supports many crypto assets, copy trading, and leverage of up to 50 times on selected trading pairs.
The HYPE token was distributed through an airdrop to more than 90,000 users in November 2024. The source associated the positive response with broad token distribution and the absence of venture-capital involvement. HYPE serves as both a utility token for the Hyperliquid ecosystem and a governance token. The total supply is capped at 1 billion HYPE, with more than 76% allocated to the user community.
CoinCodex listed Hyperliquid with ticker HYPE, launch 2024, market capitalization on June 15, 2026 at $17 billion, and function as decentralized futures trading platform.
Ethereum is a blockchain platform designed for smart contracts and decentralized applications. Its native currency is Ether, or ETH. Developers can use Ethereum to create tokens and applications for finance, gaming, social media, identity, tokenization, and other uses.
CoinCodex listed Ethereum with ticker ETH, launch 2015, market capitalization on June 15, 2026 at $212 billion, function as blockchain platform for smart contracts, and displayed price at $1,753.72, down 2.33%.
Bitmine Immersion was described as purchasing 101,901 ETH over one week for approximately $236 million to $241 million. The article said the company then held about 5.078 million ETH, equivalent to approximately 4.21% of circulating supply, after shifting to a crypto-treasury strategy in 10 months. It targeted ownership of 5% of total ETH supply.
The article said approximately 3.7 million ETH, or 73% of its holdings, were staked and generating about $264 million in annualized revenue. The remainder could create additional revenue if staked.
A quoted Bitmine update from April 27, 2026 gave a different holdings snapshot and broader asset composition: "$13.3 billion in total crypto + 'moonshots': 5,078,386 ETH at $2,369 per ETH, 200 Bitcoin, a $200 million stake in Beast Industries at MrBeast, and other assets." The quoted update was dated April 27 and described total ETH at a price of $2,369, while the surrounding June article discussed a later purchase and a market price near $1,753.72. They represent different dated snapshots.
Ethereum staking creates rewards but introduces validator, slashing, liquidity, tax, and infrastructure considerations. A large treasury company accumulating ETH can support market demand while also creating concentration if the company later sells or if its strategy changes.
XRP launched in June 2012. It was developed by David Schwartz, Jed McCaleb, and Arthur Britto, who formed OpenCoin with Chris Larsen. Developers retained or gifted 80% of the initial supply to the company, later renamed Ripple. Most of Ripple's XRP holdings were described as being in escrow.
XRP uses the XRP Ledger Consensus Protocol rather than proof of work or proof of stake. Participants can select validators they trust to behave honestly. The network is designed for fast, low-cost transfers and is used by Ripple in products such as On-Demand Liquidity, which supports cross-border payments through partnerships with exchanges.
CoinCodex listed XRP with ticker XRP, launch 2012, market capitalization on June 15, 2026 at $76 billion, and function as efficient digital currency.
Ripple, Mastercard, JPMorgan, and Ondo Finance completed a pilot in which tokenized U.S. Treasuries could be redeemed and settled across a public blockchain and traditional banking infrastructure. The transaction began with Ondo Finance redeeming OUSG, its tokenized Treasury fund, for Ripple on the XRP Ledger. Mastercard's Multi-Token Network routed the instructions through Kinexys, JPMorgan's blockchain payment platform. JPMorgan delivered U.S. dollars to Ripple's Singapore bank account.
Mastercard stated: "Today, Mastercard, Ondo Finance, Kinexys by JPMorgan, and Ripple successfully completed a landmark transaction connecting a public blockchain with interbank settlement rails. Together, we're laying the groundwork for 24/7 global markets that never close." The transaction connected public-chain infrastructure to banking rails. It did not mean XRP itself was used for every step of settlement, and it did not establish that the XRP Ledger had become a national payment network.
Solana is a high-performance smart-contract platform founded by Anatoly Yakovenko in 2018. Its mainnet launched in March 2020. Solana combines a Proof-of-History mechanism with proof of stake. The network is designed to process thousands of transactions per second at low cost. The article said SOL transfers often cost less than $0.001.
CoinCodex listed Solana with ticker SOL, launch 2020, market capitalization on June 15, 2026 at $42 billion, and function as high-performance blockchain platform for smart contracts.
South Korea's Shinhan Card, described as the country's largest card issuer, partnered with the Solana Foundation to test stablecoin payments for its 28 million cardholders. The proof of concept was to examine payments between customers and merchants on Solana's testnet. The trial focused on real-world payment scenarios, security and reliability of non-custodial wallets, hybrid models combining traditional finance and decentralized tools, DeFi services built with oracle technology, and connecting real-world transaction data with blockchain networks.
Non-custodial wallet security is a major deployment condition. Convenience, merchant adoption, regulation, user recovery, and interoperability would need to be tested before large-scale use.
Solana-based tokenized real-world assets were reported to have passed $2.5 billion for the first time. Solana developers were also working on post-quantum security because quantum computing could threaten existing digital-signature systems. The Solana Foundation identified Falcon as a likely resistant signature scheme. Anza and Jump Crypto's Firedancer were described as building early implementations. The foundation said a future migration could be managed without a major reduction in network performance.
The article also referred to the Solana Accelerate conference in Miami on May 5. Because the surrounding article was dated June 2026 and described the conference as upcoming, the source contains a date inconsistency. The conference information was retained in the original list but should be independently verified.
NEAR Protocol is a high-throughput blockchain built around sharding. It emphasizes rapid finality, scalable execution, private computation, and applications related to artificial intelligence. Smart contracts can be written in Rust and JavaScript. Contract developers receive 30% of the gas fees burned when their contracts are used.
NEAR Intents is a multichain transaction framework in which a user states a desired result and independent parties compete to fulfill it. A common use is swapping assets across networks without manually choosing every step.
CoinCodex listed NEAR with ticker NEAR, launch 2020, market capitalization on June 15, 2026 at $3.2 billion, displayed price at $2.23, down 4.63%, and function as AI- and scalability-focused blockchain.
A dynamic resharding upgrade scheduled for June 2026 was intended to let the network add capacity automatically as usage increased. NEAR was positioning itself for autonomous AI agents that could make frequent, low-cost transactions.
Trezu's Confidential Treasuries were described as using NEAR for private multisignature accounts, payroll, balance management, and cross-chain payments. NEAR AI was described as anonymizing personally identifiable information locally before prompts were sent to services such as ChatGPT, Claude, and Gemini.
The article also warned that part of the rally appeared narrative-driven. Fees, actual usage, AI adoption, and revenue capture would need to grow enough to support renewed market attention.
Bittensor is a decentralized peer-to-peer market for machine intelligence. The network is divided into specialized subnets for tasks such as text prompting, transcription, image generation, or audio generation. The article referred to more than 30 operational subnets and later stated that more than 120 Bittensor subnets existed in total. The difference appears to distinguish active operating subnets from the broader total ecosystem.
Bittensor uses Yuma Consensus. Miners provide machine-learning computing resources, validators evaluate work, and TAO tokens reward and pay for those services. Users access machine-learning services with TAO.
CoinCodex listed Bittensor with ticker TAO, launch 2021, market capitalization on June 15, 2026 at $3 billion, and function as decentralized platform for machine intelligence.
Subnet 3, called Templar, released Covenant-72B, a large language model trained across more than 70 contributors. The model was trained on 1.1 trillion tokens and received an MMLU score of 67.1. The article compared that scale with Meta's Llama 2 70B.
Templar stated: "We just completed the largest decentralised LLM pre-training run in history: Covenant-72B. Permissionless, on Bittensor subnet 3. 72B parameters. ~1.1T tokens. Commodity internet. No centralized cluster. No whitelist. Anyone with GPUs could join or leave freely."
TAO gained 16% in one week and 87% in one month. The article said it remained about 59% below a $776 all-time high. Other AI-linked tokens were reported as follows: RENDER up 31%, FET up 60%, VVV up 37%, VVV nearly 300% year to date.
Subnet-specific tokens such as Targon, Lium, and Score were also mentioned. Their prices can reflect a smaller market, lower liquidity, and project-specific risks even when the parent Bittensor ecosystem is active.
Sky is a decentralized-finance protocol that issues USDS, a stablecoin intended to track the U.S. dollar. Users can lock collateral such as ETH into smart contracts and mint USDS against it. The system is overcollateralized: the collateral must be worth more than the minted stablecoin, and a position can be liquidated if its collateral value falls.
SKY is used for decentralized governance. Sky began under the name Maker in 2014, and its original stablecoin, Dai, launched in late 2017. Multi-Collateral Dai launched in 2019 and expanded collateral options beyond ETH.
CoinCodex listed Sky with ticker SKY, launch 2015, market capitalization on June 15, 2026 at $1.3 billion, and function as decentralized-finance project.
The article reported that Sky generated $338 million in protocol revenue in 2025, increased USDS supply by 74% year over year to $9.2 billion, reduced quarterly core operating expenses by 63% year over year to $8.8 million, maintained more than $4 billion in instant-redemption liquidity through its Peg Stability Module, supported zero-slippage swaps between USDC and USDS, increased holders from 509,000 to 582,000, and saw the Sky Savings Rate decline from 12.5% to 4% as DeFi rates compressed.
The growth in supply and holders can indicate adoption, while the falling savings rate shows that protocol economics can change as market interest rates and demand change. USDS remains dependent on its collateral, liquidation system, smart contracts, governance, and liquidity mechanisms.
Stellar focuses on payments and asset tokenization. It was founded by Joyce Kim and Jed McCaleb, who had also been involved in XRP. Stellar uses the Stellar Consensus Protocol, which is neither proof of work nor proof of stake. The minimum transaction fee is 0.00001 XLM, although the article said users would commonly pay around 0.0001 XLM.
Stellar includes a built-in decentralized exchange for assets issued on the network. Soroban is its smart-contract platform.
CoinCodex listed Stellar with ticker XLM, launch 2014, market capitalization on June 15, 2026 at $6.9 billion, and function as blockchain focused on payments and tokenization.
XLM was reported to have risen 72% in seven days after the Depository Trust & Clearing Corporation announced plans to enable tokenization of DTC-custodied assets on Stellar. The assets were expected to become available on Stellar in the first half of 2027.
The integration covers the lifecycle of tokenized assets, including issuance, corporate actions, reporting, conversion, and settlement. It followed a December 2025 SEC no-action letter related to tokenizing certain custodied assets such as Russell 1000 stocks, major index ETFs, and U.S. Treasuries. DTCC planned limited live transactions in July 2026 and a broader launch in October 2026, with Stellar support arriving later.
Stellar was described as the second public blockchain connected to the service after Canton Network. The distinction was significant because Stellar tokens are native base-layer assets rather than tokens created through Ethereum-compatible smart contracts.
BNB was launched by Binance in 2017. It has two principal functions: a utility and governance asset within the Binance ecosystem, and the native asset used to pay transaction costs on BNB Chain. BNB holders can receive reduced trading fees and access Binance products such as Launchpad, Launchpool, and card cashback. BNB Chain is an Ethereum-compatible network with lower fees and supports EVM-compatible decentralized applications. BNB was previously called Binance Coin and has since been rebranded.
CoinCodex listed BNB with ticker BNB, launch 2017, market capitalization on June 15, 2026 at $83 billion, displayed price at $601.30, down 0.78%, and function as BNB Chain's native asset and a token used in the Binance ecosystem.
The 33rd quarterly BNB burn removed 1.44 million BNB, reported as worth approximately $12 billion at the time. The previous burn removed 1.59 million BNB, worth $1 billion. The most recent burn was smaller by token count but larger by dollar value.
The burn reduced supply to 137.7 million BNB. BNB's auto-burn mechanism considers the token price and the number of blocks produced during the quarter. The stated supply target was 100 million BNB.
BNB was reported as rising 20.6% against the U.S. dollar over 30 days, compared with Bitcoin at 5.2% and Ethereum at 3.8%. A Coinbase listing was described as notable because Binance remained BNB's central ecosystem while also competing with Coinbase. The article characterized the listing as a possible sign of a more favorable regulatory environment, while noting that BNB had previously faced securities-law controversy because it was created and sold by Binance.
Burns reduce supply according to the mechanism, but token value can still decline. Exchange dependence, regulatory treatment, smart-contract risk, governance concentration, and network usage affect the investment case.
Other Cryptocurrencies Named
CoinCodex named Bitcoin, Ethereum, Litecoin, Polygon, and Solana as examples for beginners because they have longer histories, substantial liquidity, established exchanges, and more educational resources. WazirX's educational FAQ also named Bitcoin, Ethereum, Tron, Ripple/XRP, and Litecoin among popular cryptocurrencies, while clarifying that popularity does not establish quality.
Other categories mentioned across the sources include altcoins, Layer 1 networks, Layer 2 scaling systems, meme coins, privacy coins, decentralized-finance tokens, AI-related tokens, payment and tokenization networks, non-fungible tokens, mobile-mining projects, exchange ecosystem tokens, and tokenized real-world assets.
Dogecoin, Litecoin, Cardano, Tron, Polygon, and other assets were mentioned in menus, examples, tags, or navigation, but the sources did not provide enough detailed project-specific information to treat those mentions as full investment analyses.
Safety and Scams
The sources repeatedly warned against relying on social-media rumors, guaranteed returns, or unexplained presales. A balanced research process should identify the project's legal entity and founders, the token contract and blockchain, whether the token is mintable, burnable, pausable, upgradeable, or controlled by an administrator, how much supply is held by insiders, whether vesting schedules are disclosed, whether liquidity is locked and whether a lock can be bypassed, whether audits were independent and current, whether a wallet can be upgraded or drained, whether the project can print more tokens, whether a presale has refund or vesting terms, whether an airdrop requires a seed phrase or excessive permissions, whether yield comes from fees, emissions, borrowing, subsidies, or another source, whether a stablecoin's reserves are redeemable, whether an exchange holds assets in custody and what protections apply, whether an influencer is being compensated, and whether profit claims are realistic and documented.
The Aalto Investment Club disclaimer stated that nothing in its material should be treated as investment advice, that no project or company was endorsed, and that readers should invest only money they could afford to lose. CoinCodex similarly warned that cryptocurrency is risky and volatile even for established assets.
Some smart people will figure out some useful things with crypto, and I do not want my Fear of Missing Out to affect other aspects of my financial plan.
This was Francis Bayes, a White Coat Investor columnist, writing his crypto investment thesis in 2021. He said the first part of the thesis had not developed as expected because people had also used crypto to scam others. He continued to hold because he did not want fear of missing out to damage other parts of his plan.
His allocation at the time was 98% stocks, all held in index funds, and 2% crypto. He described 1% to 5% as a range he considered reasonable for exploiting volatility and possibly reducing portfolio correlation with stocks. He considered the difference between 1% and 2% negligible for the overall portfolio, while moving from 2% to 5% would add meaningful risk and emotional pressure. This was his personal allocation, not a universal recommendation.
Bayes rebalanced stocks annually using new contributions to retirement accounts. Crypto was handled more actively: he bought when crypto reached 0.8 times the target allocation, equal to 1.6% of the portfolio, and sold when crypto reached 1.25 times the target allocation, equal to 2.5%. Proceeds from crypto sales went into stocks. Crypto purchases came from cash in his checking account.
He wrote the thresholds into a plan and used conditional formatting in Google Sheets or Microsoft Excel to change a cell color when the crypto allocation moved outside the target range.
Behavioral discipline did not remove the difficulty of following the plan. Instead of buying a large lump sum during the summer 2022 crash, Bayes bought in small amounts because he feared another decline. When crypto exceeded 2.5% in fall 2024, he did not sell at Bitcoin prices of $90,000, $95,000, or $98,000 because he feared missing further gains. He eventually sold the excess while writing about the need to practice his own plan.
A commenter asked why proceeds were not used to buy more index funds rather than being held as cash. Bayes explained that he preferred to use checking cash for the taxable stock purchase because he had other near-term uses for the cash, and he wanted to take gains before a possible crash. He also noted that his exchange charged no transaction fee but did charge a spread. Another commenter suggested that buying more index funds with new cash could be a useful future behavior.
Heather Townsend's January 2022 view was that she had not found evidence-based research supporting crypto allocation to client portfolios and that its risk-to-reward ratio did not meet her criteria. She compared it with the dot-com bubble and questioned whether projects such as Pets.com and theGlobe.com would survive. She also stated that governments might develop their own digital currencies rather than adopt Bitcoin, Ether, or Dogecoin.
Her conclusion was that crypto might remain, but investors who participate should treat it as a limited "play fund," keep it separate from other savings goals, and invest no more than 5% of net worth. That limit was specific to her February 2022 article and was not presented as a universal threshold.
At the end of January 2022, Townsend Financial described the overall crypto market as down 7% and Bitcoin as down 20% for that year. The comparison was specific to that date.
Bitcoin rose more than 120% in 2024. In December 2024, it traded above $90,000 and then surpassed $100,000 a few days later. Those figures describe calendar-year or point-in-time performance and do not represent the return of every investor. A personal portfolio can experience a different result because of purchase dates, rebalancing, taxes, fees, and the amount allocated.
A June 2026 CoinCodex page displayed a broader market snapshot of total crypto market capitalization at $2.22 trillion, down 1.66%, Bitcoin dominance at 58.36%, down 0.26%, 24-hour crypto volume at $356.97 billion, up 21.22%, Bitcoin at $64,553, down 2.05%, S&P 500 at 7,421.76, down 1.21%, Gold at $4,320.95, down 0.44%, and USD/EUR at €0.87, up 0.82%.
The same page gave Bitcoin's price as $66,150 in its Bitcoin section, while a later data table listed a $1.33 trillion Bitcoin market capitalization. The page's global snapshot showed a $2.22 trillion total crypto market rather than a Bitcoin-only value. These figures were captured at different points or in different components of the page and should be treated as time-sensitive snapshots rather than permanently fixed values.
The CoinCodex article said Bitcoin had recovered from a June 6 low of $59,000. Geoffrey Kendrick of Standard Chartered was quoted describing $59,000 as the bottom of the current cycle and expecting Bitcoin to reach $100,000 and Ether to reach $4,000 by year-end. The article also cited more than $5.72 billion in outflows from spot bitcoin ETFs since the second week of May, anecdotal claims that some ETF investors were selling to raise money for a SpaceX IPO, a need for U.S. spot bitcoin ETF flows to return to positive net daily inflows, a planned U.S.-Iran peace agreement expected to reduce geopolitical uncertainty, lower oil prices and expectations of lower Treasury yields, potentially supporting risk assets, and Michael Saylor announcing that Strategy had purchased 1,587 BTC for $100 million at an average price of $63,024.
Institutional accumulation, ETF flows, government policy, geopolitical developments, and large corporate purchases can influence market expectations. The listed events do not establish a guaranteed future price.
CoinCodex identified Bitcoin as the leading cryptocurrency by market capitalization and listed it as a decentralized peer-to-peer cryptocurrency. Its June 15, 2026 data table reported a Bitcoin market capitalization of $1.33 trillion. The page's price ticker showed $64,553 at one point, while the Bitcoin section quoted $66,150 after a reported 4.5% seven-day increase.
Bitcoin is a decentralized peer-to-peer cryptocurrency introduced in 2008 and launched in early 2009. It introduced the blockchain model, uses proof of work, and rewards miners who add blocks. Its fixed issuance schedule is designed to limit supply to 21 million BTC.
Bitcoin transactions can be sent at any time and can be settled without a bank. Users can hold their own private keys and self-custody rather than relying on an exchange. The network's open transaction history and proof-of-work sequence make altering recorded transactions extremely difficult.
Competing Interpretations of Bitcoin's Value
Supporters of bitcoin described it as a secure store of value with a fixed supply. They cited the following properties: transactions can operate 24/7, Bitcoin can be sent globally without a conventional intermediary, the supply has a fixed cap of 21 million, Bitcoin can be divided into very small units, it can be held without dependence on a bank, users can control private keys and self-custody, its monetary policy cannot be expanded by a government in the same way as fiat currency, it can be transferred globally with low friction, and it is available through many exchanges and trading pairs.
A commenter described Bitcoin as "the world's most liquid asset" and said it could be bought or sold around the clock. Other comments argued that it was faster to transfer internationally than conventional banking rails and that its fixed cap made it different from fiat currencies, gold, and real estate.
Supporters also compared bitcoin's growth with other technologies. They described adoption as moving from a niche experiment toward a multi-trillion-dollar asset, with ETFs, institutional interest, national discussion, mining, payment experiments, and broader public awareness. One commenter stated that bitcoin had reached a $2 trillion market capitalization and described its path from an asset with little value to one larger than most national economies and many companies. These were advocacy claims rather than guarantees.
Skeptics argued that bitcoin still had limited practical use for ordinary legal transactions in the United States. They contrasted its properties with assets that produce income: stocks represent earnings, bonds pay interest, real estate can produce rent, and Bitcoin does not automatically produce cash flow. They also questioned whether future adoption would occur. Bitcoin proponents had predicted widespread payment use for more than a decade, but bitcoin was still not commonly used for groceries, rent, payroll, or everyday purchases in many countries.
Other concerns included: Bitcoin has a much shorter history than gold, real estate, or cash; past returns can attract buyers for the wrong reason; a large market capitalization has not necessarily reduced volatility; a network may remain valuable without being widely used as everyday money; self-custody can be technically difficult, and a hardware wallet or seed phrase can still be lost or compromised; a private key may reduce confiscation risk, but physical coercion, seizure, legal restrictions, or threats can still affect ownership; Bitcoin could continue to rise, remain flat, decline, or lose most of its value; a successful future for bitcoin would not guarantee that every price forecast or entry point was correct; and past growth from a very low starting value could not safely be projected forward indefinitely.
A White Coat Investor response calculated that bitcoin had risen from approximately $0.30 in 2011 to $94,420 in early January 2025, equivalent to about 147% annualized. The response argued that repeating that rate would produce implausibly large future values: approximately $4 million per bitcoin in four years, or a total value comparable to the world's net worth within six years. The point was that extraordinary historical growth should not be treated as a normal expected return.
The same response stated that $4 million could be possible if bitcoin became the world's sole currency, but that $10 million in today's dollars appeared highly unlikely. It also stated that a long-term investor would need to decide how much lifetime savings could be exposed to that outcome. The author said he would consider approximately 5% for someone who genuinely believed in bitcoin and understood the risk. That was presented as a discussion of sizing, not a prediction.
The White Coat Investor author's criteria for including an asset in a portfolio were: it produces earnings, interest, rent, or another form of economic output; it has a track record of at least hundreds of years; and it does not have a large following that the author regarded as religious or gambling-oriented.
One commenter said they held slightly less than 3% bitcoin and believed its allocation should eventually be higher. The exchange continued to distinguish between a general belief that an asset may rise and willingness to place enough money in it that a favorable outcome would make a meaningful difference.
Gold Comparisons
Bitcoin supporters frequently compared it with gold. A commenter argued that gold's nominal price increased because dollars lost purchasing power. The comparison used a 1978 gold price of about $193 per ounce and a later price near $2,680 per ounce. The commenter calculated a 5.6% compound annual growth rate, then added an estimated 1.8% annual increase in mined gold supply to arrive at a 7.4% rate comparable to monetary-supply expansion.
Gold supporters responded that gold, art, collectibles, watches, real estate, and stocks also derive much of their value from what other people are willing to pay. Critics of bitcoin argued that its market capitalization and recent adoption do not prove it will capture a large monetary premium.
Confiscation, Censorship, and Self-Custody
Some supporters characterized bitcoin as uncensorable and unconfiscatable because a user who controls the private key can transfer it without asking another institution for permission. Critics replied that "less confiscatable" may be more accurate than "unconfiscatable." Government seizure, coercion, inheritance disputes, compromised keys, and physical threats can still affect ownership.
Supporters also cited self-custody as a way to reduce dependence on exchanges. Critics emphasized that self-custody transfers responsibility to the owner and creates risks when software, hardware, passwords, recovery phrases, or backups are handled incorrectly. A well-established exchange may be more convenient for recurring purchases, while a hardware wallet may provide stronger control after purchase.
Adoption, Payment Use, and Regulation
One commenter stated that El Salvador had made bitcoin legal tender and that businesses there accepted it. Other comments said payment use remained limited, although Lightning Network payments, gift cards, bars, and other experiments existed. U.S. capital-gains treatment was described as a reason bitcoin holders might prefer to hold rather than spend.
A commenter said Russian foreign transactions were being conducted with bitcoin, but this was presented as commentary rather than a developed use-case analysis. Other comments referred to possible national strategic bitcoin reserves and to proposed U.S. adoption. The existence or size of such a reserve was not established by the investment case itself.
Comments also noted that bitcoin had reached a $2 trillion market capitalization in roughly 16 years, was mined without a company CEO or marketing department, and had developed a substantial market. Skeptics replied that adoption predictions had repeatedly been premature. They also cited multiple "crypto winters," when public attention disappeared after prices fell.
Return and Forecasting Warnings
A White Coat Investor response calculated that bitcoin had risen from approximately $0.30 in 2011 to $94,420 in early January 2025, equivalent to about 147% annualized. The response argued that repeating that rate would produce implausibly large future values: approximately $4 million per bitcoin in four years, or a total value comparable to the world's net worth within six years. The point was that extraordinary historical growth should not be treated as a normal expected return.
The same response stated that $4 million could be possible if bitcoin became the world's sole currency, but that $10 million in today's dollars appeared highly unlikely. It also stated that a long-term investor would need to decide how much lifetime savings could be exposed to that outcome. The author said he would consider approximately 5% for someone who genuinely believed in bitcoin and understood the risk. That was presented as a discussion of sizing, not a prediction.
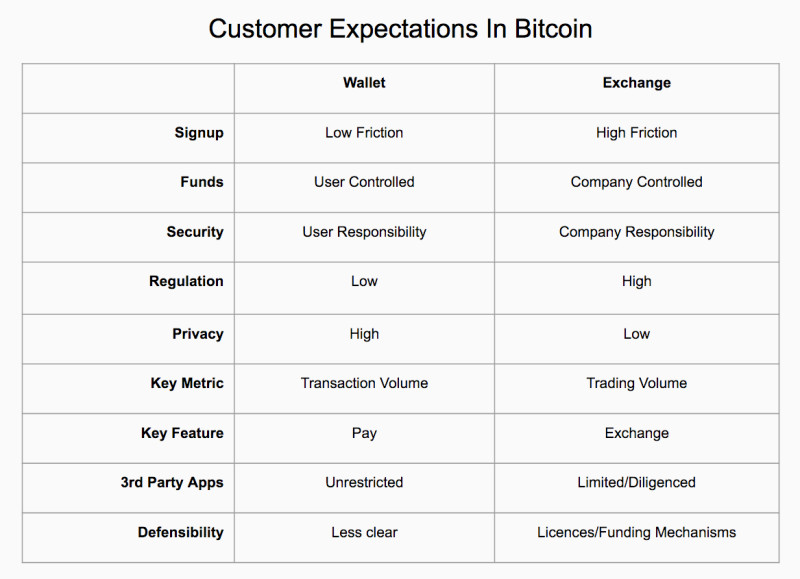
Comments on “How to Invest in Crypto Coins with a Clearer Step-by-Step Plan”
No comments yet. Be the first to share your thoughts.